Bank of Ghana urges media to verify fintech licences and distinguish fraud from cyberattacks
Date: 2026-10-12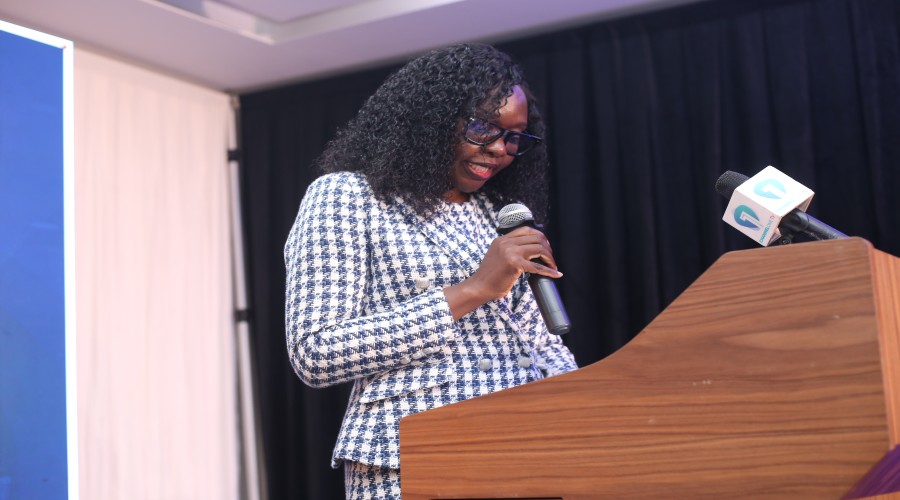
By: Nana Appiah Acquaye
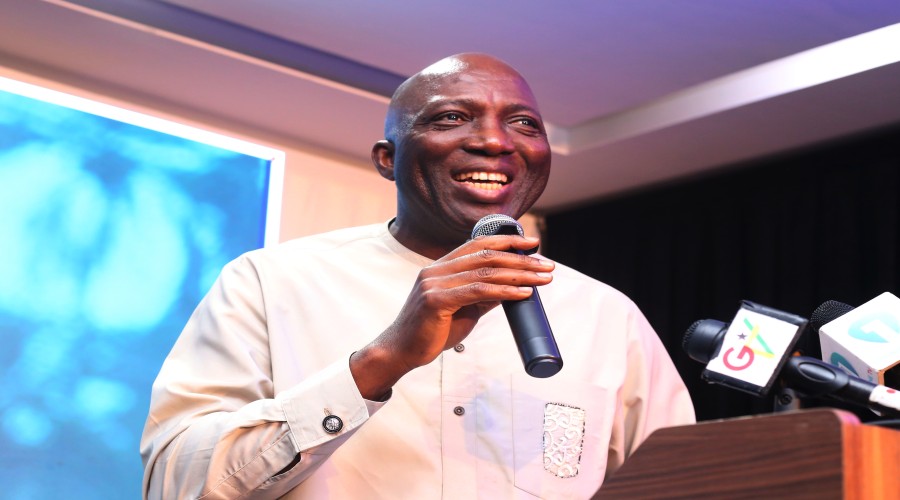
The Head of the Licensing
and Authorization Office at the Bank of Ghana’s Fintech and Innovation
Department, Anita Ayivi has urged media organisations to verify the regulatory
status of digital financial service providers and ensure accurate reporting of
incidents involving fraud, cybersecurity and service disruptions.
Speaking at the Fintech
Media Development Series in Accra, held under the theme “Understanding Fintech,
Building Trust, Telling the Real Story,” Ayivi said responsible reporting was
essential to helping consumers make informed decisions and maintaining confidence
in legitimate digital financial services.
She encouraged journalists
to consult the Bank of Ghana’s published information on licence categories,
licensing requirements and approved institutions before reporting on the
regulatory status of fintech companies.
“We encourage the media to
take these checks as part of the reporting process and where the position is
unclear to seek clarification before publication,” she said.

Ayivi noted that the
financial sector and the media had become increasingly interconnected as
financial services grew more complex and consumers accessed products through
channels that had not existed a few years ago.
She said the media had an
important role in helping the public understand these developments accurately
and in their proper context, adding that journalists needed to understand how
Ghana’s digital financial ecosystem operates, including the respective roles of
the regulator and industry.
The Bank of Ghana official
explained that the Payment Systems and Services Act, 2019 (Act 987), provides
for licensing and authorisation, technology, security and controls, oversight,
reporting procedures and consumer protection.
She stressed that fintech
was not a single licence, institution or activity, noting that different
categories of institutions operated under distinct permissible activities and
regulatory requirements.
The Bank of Ghana licenses
and oversees dedicated electronic money issuers, payment service providers and
other non-bank providers, including payment and financial technology service
providers and digital credit service providers, within its mandate.
“The distinction matters in
reporting because the fact that an institution uses technology does not
necessarily mean it is authorised to provide every financial service,” Ayivi
said.
She added that a commercial
partnership, an application appearing in an app store or a product being widely
advertised should not, on its own, be considered evidence of regulatory
approval.

Ayivi also urged journalists
to distinguish between fraud, cybersecurity incidents, service disruptions and
regulatory breaches, warning that these events should not automatically be
treated as the same.
“A service being temporarily
unavailable does not, without further facts, establish that the institution has
been hacked. An allegation of fraud does not by itself establish a
cybersecurity breach. Likewise, a regulatory matter should be reported on the basis
of the applicable regulatory requirement and verified facts,” she said.
According to her,
understanding what has actually occurred before characterising an incident is
important because the distinctions can significantly influence how customers
interpret a report.
She further called on media
organisations to verify the regulatory status of digital lending platforms
before publishing their advertisements or promotional content.
“Before carrying
advertisements or promotional content for a digital lending platform, media
organisations should make verification of regulatory status part of their due
diligence,” she said.
Ayivi said the Bank of Ghana
had repeatedly published notices concerning digital loan applications operating
without the required licence or authorisation. These notices, she explained,
had highlighted concerns about customer data privacy, consumer protection and
compliance with regulatory standards, while advising the public not to engage
with unlicensed loan providers.
“An attractive advert or a
downloadable application should therefore never substitute for checking whether
the provider is authorised to offer the financial service it is promoting,” she
said.
She noted that Act 987
provides for consumer protection principles, responsibilities of electronic
money issuers and payment service providers, complaints procedures and
transparency requirements.