By: Dr Isaac I.
SISSOKHO, expert in Governance, Regulation and Digital Development Strategy
WhatsApp, YouTube, TikTok, Facebook, Netflix: these services are part of
the daily lives of tens of millions of Africans. In telecoms jargon they are
called “OTT”, for over-the-top: services delivered via the Internet, on
top of operators’ networks, without owning or operating them. Their success is
also that of African connectivity. But it raises a question Africa has chosen
to bring before the highest body of the International Telecommunication Union
(ITU): the balance between those who build the networks and those who capture
most of their value.
Adopted in Dubai in 2018 and left unchanged in Bucharest in 2022,
Resolution 206 instructs the ITU to study the economic and regulatory
implications of OTT services and encourages dialogue between operators,
platforms and regulators. The African common proposals, prepared under the
auspices of the African Telecommunications Union (ATU), go further: exploring
mechanisms through which OTT providers would contribute to network costs and
universal service, tasking the ITU Telecommunication Development Bureau with
guidelines on “fair and sustainable” mechanisms, and recognising the sovereign
right of States to regulate these services. The text also sets safeguards:
respect for the open Internet, network neutrality and competition, and no
application blocking. Africa is not asking for the Internet to be restricted.
It is asking for its funding to be shared more fairly.
The figures make the imbalance tangible. According to Sandvine, eight
groups (Alphabet, Meta, Netflix, Microsoft, TikTok, Apple, Amazon and Disney)
generate around two-thirds of global Internet traffic. On mobile networks, Meta
alone accounts for 22%, Alphabet for 20% and TikTok for 12%. In Senegal, data
from the regulator, ARTP, show the shift under way: Internet traffic grew by
roughly a third in one year, international calls now make up just 0.16% of
mobile voice traffic, and subscribers send on average only four text messages a
month. In a country with a large diaspora, this reflects a massive move to
messaging and app-based calling. Meanwhile, the value of the mobile market
stagnated between 2024 and 2025, at around CFAF 525 billion (about €800 million).
OTT services thus enter African markets from the low end. Free or nearly
free for users, funded by advertising and data, they replace services that
operators charge for, while relying entirely on the networks those operators
finance. That effort is considerable: in 2025, the Sonatel group, present in
five countries, invested CFAF 288.6 billion (about €440 million) and paid
nearly half its turnover to States in taxes, fees and dividends. Licensed
operators also contribute to universal service and bear obligations on
coverage, quality of service, subscriber identification and lawful
interception, from which platforms offering equivalent services, with profits
declared outside the continent, are largely exempt. The resulting distortion of
competition weakens still-young markets.
Africa is not alone. In Europe, operators have long called for a “fair
share” contribution from the largest traffic generators. The draft Digital
Networks Act presented by the European Commission on 21 January 2026 rules out
a mandatory levy, but creates a voluntary conciliation mechanism that the
digital giants’ associations already call a back door. In Brazil, the regulator
Anatel relaunched a consultation in March 2026 on “large users” of networks. In
South Korea, the SK Broadband–Netflix dispute ended in 2023 with a commercial
agreement, and in South Africa operators are pressing for a contribution from
streaming platforms. Everywhere, the aim is to fund traffic growth without
making consumers alone foot the bill or undermining an open Internet.
This global debate is not enough, however, to win over the major powers.
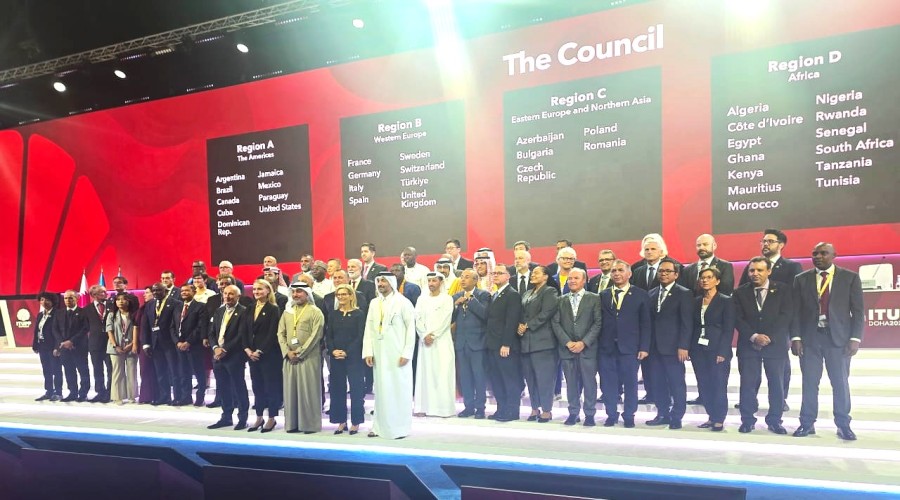
In Doha, the African proposal faces a transatlantic front. Both the European
common proposals and the Inter-American proposals, championed notably by the
United States, call for Resolution 206 to be left unchanged. Washington holds
that the ITU has no business regulating Internet services, while the European
Union, conducting its own debate, does not intend to take it global. Other
regions may be more receptive: the Arab Group has traditionally backed a
greater role for States in digital regulation, and Brazil is pursuing its own
reflection, even though the Americas region has sided with the status quo.
China and the Asia-Pacific region have not made their position public.
The balance of power is unfavourable, but not set in stone. The ITU
works by consensus, and texts are negotiated in the Working Group of the
Plenary before adoption in plenary. Between Africa’s ambitious revision and the
West’s status quo, compromises remain possible: explicit recognition of States’
right to regulate, in-depth studies on cost-sharing, capacity-building for
African regulators, and stronger consumer protection.
The negotiation also has a less familiar technical dimension. To bring
content closer to users, major platforms deploy “cache servers” in many
countries: computers installed near subscribers that store copies of the most
popular videos and content, so they need not cross the submarine cable each
time they are viewed. Usually supplied by the platforms, they are hosted by
operators or at Internet exchange points, where a country’s networks exchange
traffic directly. Platforms readily cite this equipment, and their investment
in new cables, as proof that they already contribute to infrastructure. The
reality is more nuanced. These arrangements also cut the platforms’ own costs
and ease the international transport of traffic, but not its delivery to
subscribers over national fibre, 4G and 5G antennas and rural sites, which
operators still pay for.
Here each country faces its own blind spots. In Senegal, according to
the Internet Society, slightly more than half of the thousand most visited
websites are reportedly reachable from a server in the country; yet little is
publicly known about where these servers are or what share of traffic they
serve, and the national Internet exchange point, launched in 2017, appears
little used. A strong case at the ITU also requires reliable public traffic
data and local interconnection open to all players at home.
That is why the battle will continue after Doha. An ITU resolution is
not binding on States: it recognises principles and opens areas of work, to be
given concrete form in national and regional frameworks. For Senegal, which is
overhauling its Electronic Communications Code, the challenge is twofold: to
make a clear and credible African voice heard in Doha, then to build at home a
framework in which all who profit from the networks contribute fairly, without
giving up on an Internet that is open, innovative and accessible to all.
The question Africa is raising in Doha is not that of a continent
against the digital giants. It is about the economic model of global
connectivity for decades to come. It deserves to be heard.